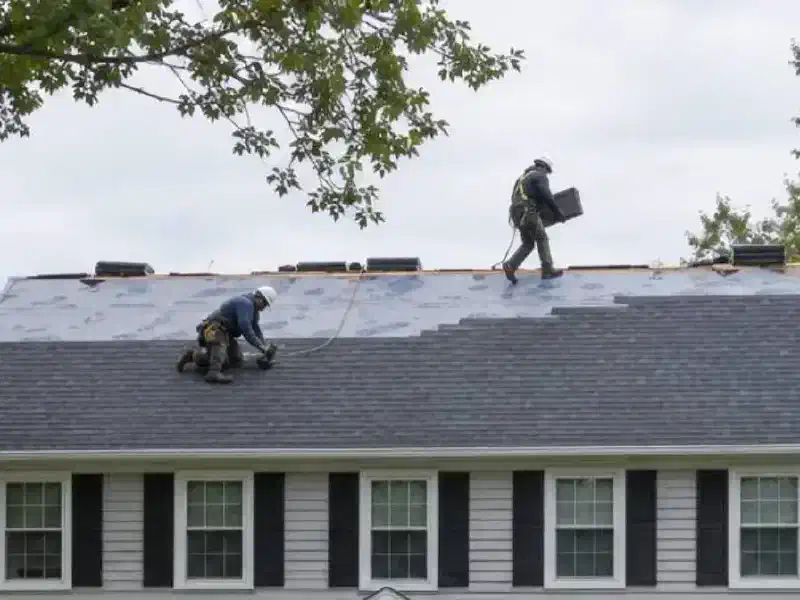
For the home you live in, a new roof is not tax deductible. The IRS treats it as an improvement, so the cost is not a deduction. It gets added to what the IRS calls your home’s basis, which can lower your tax later when you sell.
The short version
- A new roof on your own home is an improvement, and improvements are not deductible in the year you pay.
- The cost is added to your basis (what the IRS counts as your cost in the home), which can shrink your taxable gain when you sell.
- A roof repair on your own home is not deductible either.
- On a rental, a new roof is written off in small pieces over 27.5 years, while a repair is deductible right away.
- Keep every receipt, and ask a tax preparer how it fits your return. We’re roofers, not tax advisers.
Can you deduct a new roof on the home you live in?
No, you can’t deduct a new roof on your main home. The IRS says an improvement materially adds to the value of your home (opens in a new tab), considerably prolongs its useful life, or adapts it to new uses. Replacing an entire roof is on its list of improvements.
Improvements don’t come off your taxes the year you pay for them. They go onto your basis instead, which is the next section.
What does “added to your basis” mean?
Your basis is, roughly, what you’ve put into the home, and the IRS says basis is generally the amount you paid for the asset (opens in a new tab). Costs of improvements that add to the value of the property raise it.
Here is a made-up example, not a real job. Say you paid $400,000 for a house, and later a new roof costs $25,000. Your basis goes from $400,000 to $425,000.
The IRS says the amount you add is your actual cost (opens in a new tab), including all costs for material and labor, except your own labor, and all expenses related to the improvement. In plain terms, tear-off, haul-away and permits count along with the shingles.
How does a higher basis save you money?
It lowers the profit the IRS sees when you sell. Profit is roughly the sale price minus your basis, so a bigger basis means a smaller profit.
For many sellers it may never matter. The IRS says you may be able to exclude up to $250,000 of that gain from your income, or up to $500,000 (opens in a new tab), if you owned and lived in the home for at least 2 of the last 5 years. A seller who clears those tests and stays under the limit owes no tax on the gain, with or without the roof receipts.
The roof still earns its keep on the sale itself, because buyers and inspectors notice an old one.
Is a roof repair deductible when a replacement is not?
No, a repair on your own home isn’t deductible either. The IRS draws the line like this: a repair keeps your home in an ordinary, efficient operating condition (opens in a new tab) and doesn’t add to its value or prolong its life. You can’t deduct repair costs and generally can’t add them to your basis.
There’s one catch. Repairs done as part of an extensive remodeling or restoration count as improvements. So fixing a few shingles is a plain repair, and a repair that’s part of a big restoration project is not.
That makes the tax angle a poor reason to pick one over the other. If you’re torn, read whether you can repair a roof instead of replacing it and have it looked at first. We give a free roof inspection and tell you which one the roof needs.
What changes if the house is a rental?
On a rental, the roof does produce a tax write-off, just not all at once. The IRS says an expense for repairing or maintaining your rental property may be deducted (opens in a new tab), while improvements, and its list names a new roof, must be capitalized, meaning spread out over years. Residential rental buildings are generally depreciated, which is the IRS word for that spreading, over 27.5 years.
| Situation | Repair (patch, a few shingles) | New roof |
|---|---|---|
| The home you live in | Not deductible | Not deductible, added to basis |
| A rental you own | Deductible | Spread over 27.5 years |
Where a given job falls on a rental can get tricky, so this is a good place for a tax preparer.
Is there a tax credit for a new roof?
The federal energy credit for home improvements has ended. The IRS says you can’t claim energy efficient home improvement credits (opens in a new tab) for any property placed in service after December 31, 2025. Tax rules change often, so check IRS.gov for the year you’re filing.
What records should you keep?
Keep the contract, the invoice, proof of payment and the permit. The IRS says to keep any receipts, canceled checks, and similar evidence (opens in a new tab) for improvements, and its record sheet has a line for the roof.
A written, itemized bid makes this easy. Our full replacement is built from tear-off, haul-away, underlayment, flashing, vents, permits and cleanup, and an estimate that lists them separately is easy to file. Our guide on what should be in a roof estimate shows what to look for.
For scale, a full replacement on a 3,500 square foot roof typically runs $22,500 to $29,500. If the size of the check is the sticking point, you can look at payment options on our financing page.
Common questions
Can I deduct a new roof if I work from home?
Maybe in part, but it’s a separate set of rules. The IRS sends anyone who uses part of their home for other than residential living, such as a home office (opens in a new tab), to Publication 936. A tax preparer can tell you if the roof comes into it.
Which costs count toward the roof’s cost?
The IRS counts material and labor and all expenses related to the improvement, but not your own labor. That would normally cover tear-off, new decking, flashing and permits on the invoice.
Who can say for sure how this works on my taxes?
A tax preparer who has seen your return can. What we’ve laid out here comes from IRS pages, and it’s general. Your situation, and the rules for the year you file, decide the answer.
What to do next
If the roof is old and you’re weighing the cost, the next step is a written bid for roof installation, which you can keep with your records.